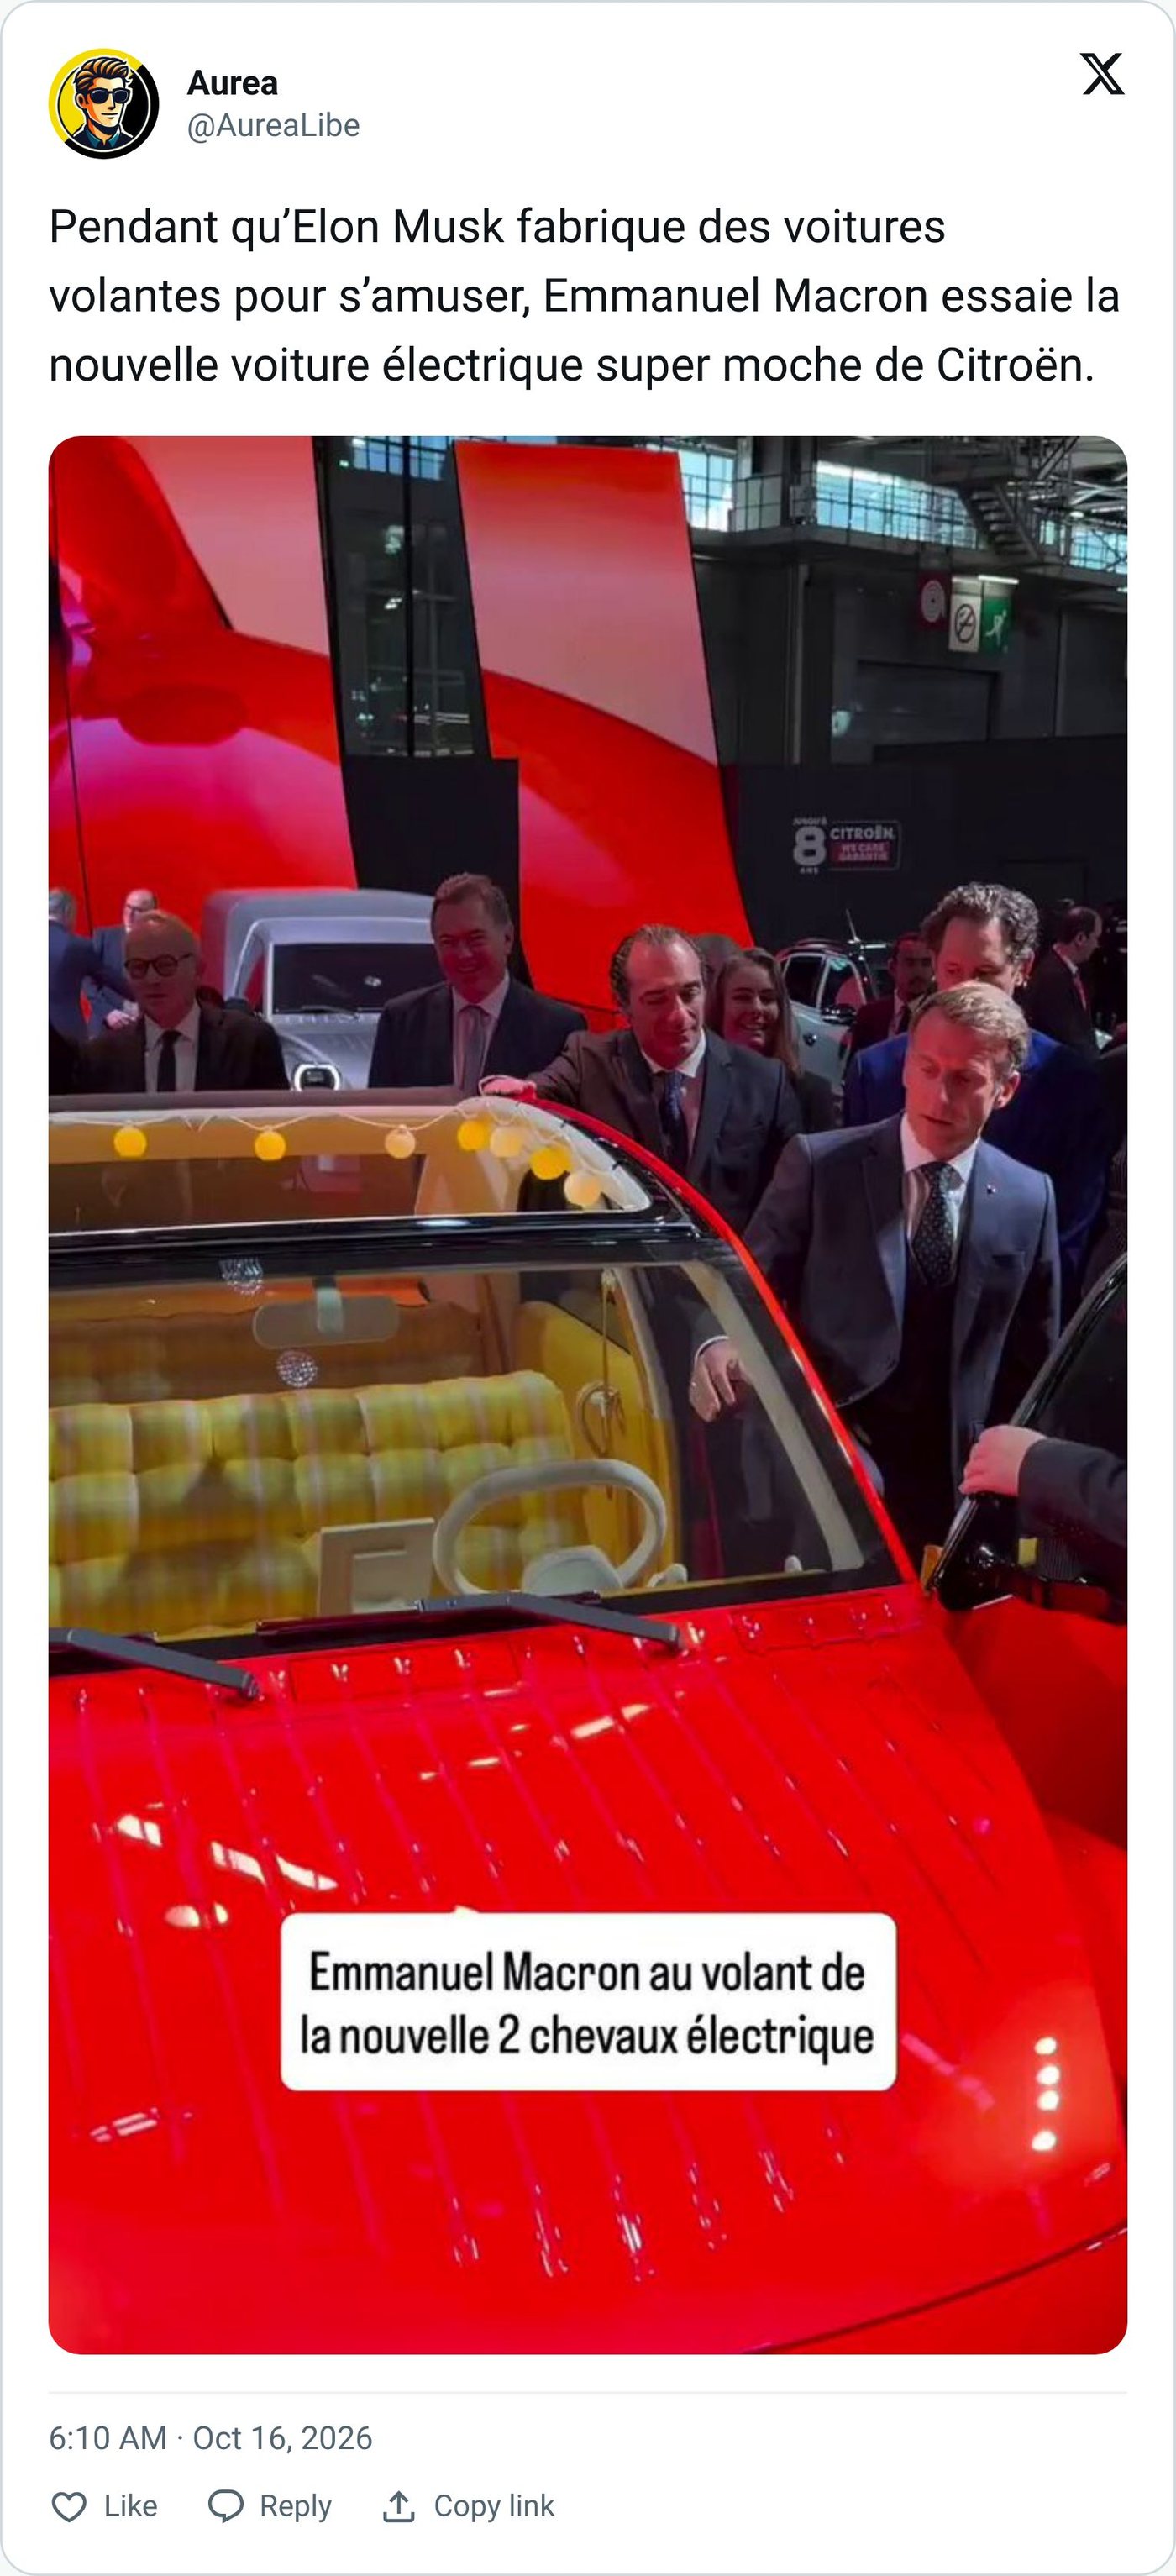
“While Elon Musk builds flying cars for fun, Emmanuel Macron tries out Citroën’s super ugly new electric car.”
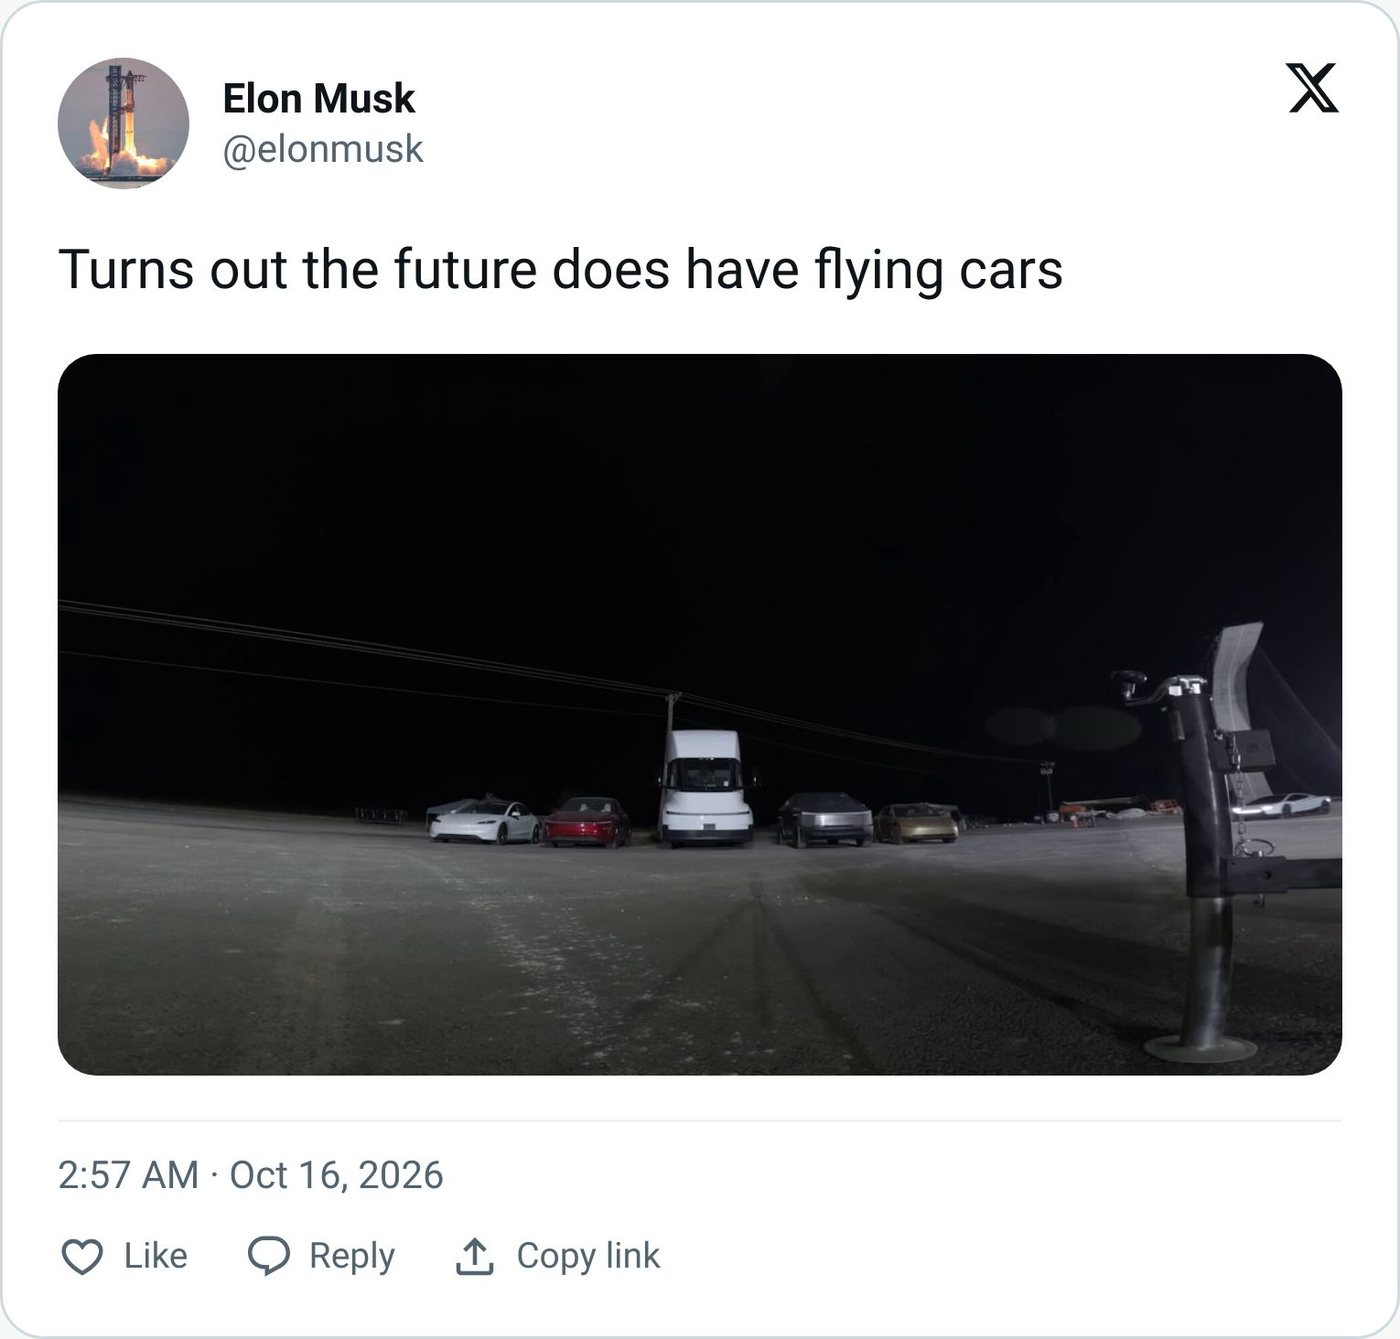
This post was doing the rounds on X last week, aimed at highlighting the ambition gap between Europe and the USA.
Because on Thursday night in Texas, Tesla’s new Roadster drove upside down along a curved ramp, launched itself into the air and landed back on its wheels - you probably saw it.
But just a few days earlier in Paris, the French president was looking slightly out of place in a “reasonably-priced” revival of the 2CV, a car Citroën stopped making 36 years ago.
One is the most talked-about car of the year. The other one is sadly the punchline.
Both are going on sale in 2028 and neither company is paying for its new car the way most companies pay for growth. For business owners, that difference matters most at the moment you win the contract you’ve been chasing.
Who is paying for the flying car
Tesla first showed off this Roadster in 2017 and said it would be on the road by 2020. It started taking deposits straight away: $50,000 for the standard car and $250,000 each for a limited Founders Series that around 1,000 people signed up for.
That’s a quarter of a billion dollars from one small group of customers, nine years before any of them can drive the car.
Last week’s launch opened the order book again. Reserving a Roadster now means paying $50,000 within ten days. Reserving the Rocket version (the one with the thrusters) means paying $250,000.
The flying car was the showmanship on display, but the deposits are the business model. Tesla’s customers are paying for the car they’re waiting for.
Why the ugly car might be the smarter business (for most of us)
Nobody gathered to watch the 2CV jump over anything. But look at how its numbers work.
Citroën didn’t have to invent a brand - it already owned one of the best-loved cars in Europe. It’s aiming at a starting price of around €15,000, which is where the mass market actually buys.
And an EU rule counts each small electric car like this as 1.3 cars towards the emissions targets every manufacturer has to hit. This means it makes the rest of the Citroën range cheaper to keep on the right side of those targets.
It’s a different method, but the same principle: someone other than Citroën is carrying part of the cost.
How growth usually gets paid for
Now compare that with how growth gets funded in a typical owner-led business.
Say you win a £2 million contract that runs over 12 months. You pay your people monthly and your suppliers within 30 days. You invoice at the end of each month, and the customer pays 60 days later.
By the time their first payment arrives, you’ve already paid out three months of costs. On a job that size, that’s more than £400,000 out of your business before you’ve seen a penny of theirs.
The job might be very profitable but it doesn’t matter yet. Growth uses up cash before it makes any money - and the bigger the contract, the bigger the hole.
That’s why so many capable business owners hesitate at exactly the moment they should be pleased. The worry isn’t whether they can do the work. It’s the thought underneath: “If we win this, can we even fund it?”
The answer they reach for is usually the overdraft, the bank or their own savings. It’s very rarely the customer.
But our customers would never pay up front
Some won’t and some trades have fixed ways of doing things. But in my experience, very few owners have actually tested it. They’ve assumed the answer and built it into how they run the business.
At your size, customer funding usually looks like one of these:
- A deposit on signing. Even 10 to 15 percent can cover the first month of work.
- Stage payments tied to milestones, so you’re never more than one stage out of pocket.
- Billing in advance for ongoing work, at the start of each month or quarter rather than the end.
- Paid trials, so a new customer’s first piece of work isn’t funded by you.
- Annual billing up front for service and maintenance contracts, sometimes with a small discount that costs you less than the cash is worth.
Go back to that £2 million contract. If you’d asked for 15 percent on signing and billed monthly in advance, most of that £400,000 hole would never have opened.
There’s a second benefit. A customer who has paid ahead is a committed customer. And when a buyer or investor looks at your business one day, cash that arrives before the work is done is something they notice and value.
Find your gap
You’ll already know your debtor days and your creditor days. Most of the time they get treated as a credit control number, just something to chase when it drifts.
Read them as a funding number instead. The gap between the two is how long you’re lending money to your customers and every contract you win on today’s terms makes that loan bigger.
Tesla’s customers paid $250,000 nine years before they could drive away. You don’t need yours to do anything like that. You just need the next big customer to stop borrowing from you.
All the best,
Gavin
P.S. How growth gets funded is often one of the first constraints we deal with in a 90-Day Sprint, before we build the plan for your next level of growth. Find out how the 90-Day Sprint works.
Tesla Roadster deposit figures from Fox Business, Jalopnik, AFP and CNN coverage, 2017 to October 2026. Citroën 2CV details from Stellantis and Paris Motor Show coverage, 2026.
Book a call and find out how to make your business more exitable